October 2026 market update
More inventory, more room to negotiate, and the slowest September for closings since 2008
Rates finally picked a direction in September, and it was not the one buyers wanted. Here is what that did to the Greater Denver Metro market, and what it sets up for the fourth quarter.
Published October 4, 2026 · September 2026 data · every figure checked against the source report
Greater Denver Metro · September 2026
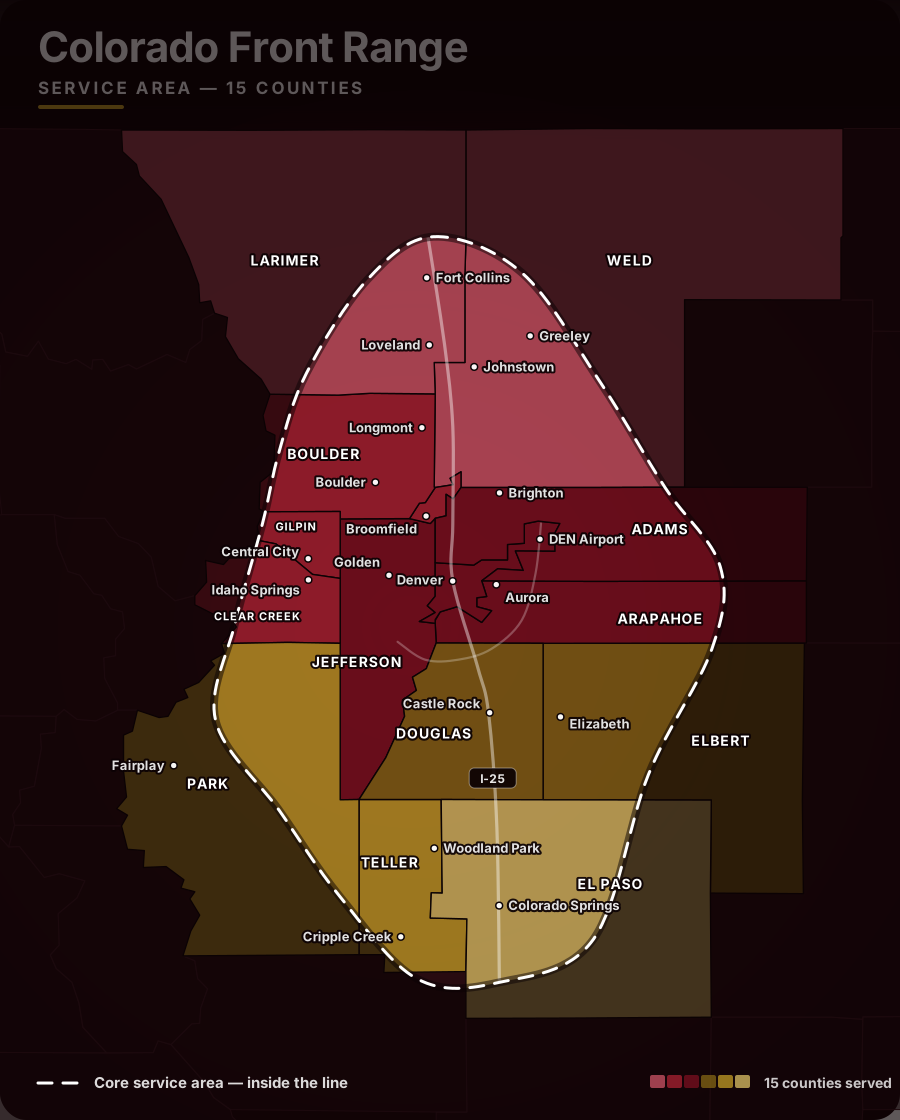
Greater Denver Metro
Adams, Arapahoe, Boulder, Broomfield, Clear Creek, Denver, Douglas, Elbert, Gilpin, Jefferson, Park counties. Statistics published by the Denver Metro Association of REALTORS from REcolorado data.
September closings came in at 2,849, down 11.71 percent from August and 21.39 percent from a year ago. That is the fewest September closings on record going back to 2008. The important caveat is timing: most homes that closed in September went under contract in August, when the 30-year fixed was near 6.7 percent. Through September it climbed every week and finished the month around 7.5 percent, and mid-month the Federal Reserve raised the federal funds rate for the first time since July 2023.
So September’s closings are a picture of August. Pending sales, at 2,908 and down 6.07 percent, are the first real read on the rate move, and that is a measured pullback rather than a retreat. The fuller effect lands in October and November closings.
Closed sales
2,849
fewest September closings on record dating back to 2008
▼-11.71%vs Aug▼-21.39%vs Sept 2025
Active listings
13,567
at month end
Median days in the MLS
32
Down from 35 days a year ago
▼3 days fasteryear over year
Months of inventory
4.76
All homes. Condos and townhomes sit at 7.21
Pending sales
2,908
The first read on September rate moves
▼-6.07%vs Aug
Close price to list price
98.45%
Up from 98.32% last September
▲+0.13 ptyear over year
For buyers, the arithmetic has improved. Inventory finished the month at 13,567 active listings and 4.76 months of supply. Condos and townhomes offer the most leverage of all: 7.21 months of inventory and a median close price of $365,500, down 6.28 percent year over year. If you are buying in that segment, price it with HOA dues and insurance in the same breath as the mortgage.
Source: DMAR. July and August as published in the August 2026 report; September as published in the September 2026 report.
View the data
| Month | Median days in the MLS | As published in |
|---|---|---|
| July 2026 | 21 | August 2026 report |
| Aug 2026 | 27 | August 2026 report |
| Sept 2026 | 32 | September 2026 report |
| Sept 2025 (reference) | 35 | September 2026 report |
Source: DMAR September 2026. A detached-only figure was not published, so it is not shown.
View the data
| Segment | Months of inventory |
|---|---|
| All homes | 4.76 |
| Condos and townhomes | 7.21 |
Since 2023, year-to-date closings have stayed within roughly six percent of one another and the overall median price within about three percent. The year-to-date median close price for detached homes is $650,000, matching each of the past two years. Year-to-date closings trail 2025 by 4.96 percent, a gap that has widened since August.
As October begins, the fourth quarter tends to reward buyers who keep moving while others wait for a fresh start after the New Year. Active listings typically taper through the fourth quarter, and some sellers will pull their homes for the holidays. Buyers who remain in the market will face less competition than at any other time of year.
Amanda Snitker, Chair of the DMAR Market Trends Committee and Metro Denver Realtor
The $1 million and above segment
The top of the market is not waiting for conditions to improve
Denver Metro, properties sold at $1 million or more.
While overall year-to-date sales are down 4.96 percent, the $1 million-plus segment is up +1.99% with 4,449 closed sales so far this year. Volume in the segment is up +3.17% to $7.30 billion, barely shy of its 2022 peak. New listings jumped +12.15% month over month, which reads as seller confidence, and buyers are not lingering: a median of 21 days in the MLS against 32 for the broader market, and 19 days for detached homes.
Source: DMAR September 2026.
View the data
| Segment | Year-to-date closed sales vs 2025 |
|---|---|
| All homes | -4.96% |
| $1M and above | +1.99% |
Source: DMAR September 2026.
View the data
| Segment | Median days in the MLS |
|---|---|
| Whole market | 32 |
| $1M and above, all | 21 |
| $1M and above, detached | 19 |
| $1M and above, attached | 23 |
Source: DMAR September 2026.
View the data
| Price band | Year-to-date closed sales growth |
|---|---|
| $1M to $1.5M | +5.60% |
| $1.5M to $2M | +5.41% |
| $2M and above | +11.11% |
| All $1M and above attached | +6.35% |
When you have room to maneuver, you can make a move, and right now Denver’s $1 million-plus market has plenty of it.
Michelle Schwinghammer, DMAR Market Trends Committee member and Metro Denver Realtor
September’s highest-priced detached sale was 31 Albion Place, Castle Rock, more than 10,000 square feet, at $7,400,000 after 44 days, in cash. The highest attached sale was 500 Adams Street, Cherry Creek North at $4,300,000, also cash.
Pricing and negotiation
What the close-to-list ratio is telling us
At 98.45 percent, the close-price-to-list-price ratio is actually a touch firmer than last September’s 98.32 percent. Sellers are not capitulating on price. What they are doing instead is paying for the gap in other currency, and with rates in the sevens that is where the negotiation has moved: rate buydowns, seller-paid concessions and adjustable-rate structures are all live at the table right now.
September 2025September 2026
Source: DMAR September 2026.
View the data
| Period | Close price to list price |
|---|---|
| September 2025 | 98.32% |
| September 2026 | 98.45% |
Colorado Springs and El Paso County · September 2026
Colorado Springs: the one market here where supply is still building
County-level statistics published by the Colorado Association of REALTORS. Every figure below is read off the published county report, and the report prints its own prior-September column, so nothing here is derived.
El Paso County sold 780 single-family homes in September, down 10.3 percent from a year ago. That is the mildest year-over-year decline of any market on this page. New listings actually rose 1.0 percent to 1,108, and the single-family median edged up 0.8 percent to $484,700.
What separates Springs from the northern counties is the direction of supply. Boulder, Larimer and Weld all tightened; El Paso loosened, with inventory up 2.5 percent to 3,619 homes and months of supply up from 4.1 to 4.3. Homes still change hands faster here than up north, at 50 days to sale against 73 and 74 days in the northern counties, and sellers took 99.1 percent of list price, the highest ratio of any county the Association reports on this page.
The condo and townhome market is the exception, and it is a sharp one. The attached median fell 12.1 percent to $297,850, attached inventory rose 5.2 percent, and months of supply climbed from 5.3 to 6.0. For an attached-home buyer, that is the most negotiating room anywhere on this page.
September 2025September 2026
Source: Colorado Association of REALTORS Local Market Update for El Paso County, September 2026, current as of October 5, 2026.
View the data
| Property type | September 2025 | September 2026 |
|---|---|---|
| El Paso County, single family | 4.1 | 4.3 |
| El Paso County, attached | 5.3 | 6.0 |
September 2025September 2026
Source: Colorado Association of REALTORS Local Market Update for El Paso County, September 2026, current as of October 5, 2026.
View the data
| Property type | September 2025 | September 2026 |
|---|---|---|
| El Paso County, single family | $481,000 | $484,700 |
| El Paso County, attached | $339,000 | $297,850 |
A note on these figures. Colorado Springs numbers on this page now come from the Colorado Association of REALTORS county report for El Paso County, rather than from PPAR and elevate MLS as on earlier pages. The Association counts El Paso County only, while PPAR covers the wider Pikes Peak region, so these counts sit below the Springs figures published here in earlier months. They are not directly comparable to those months, and earlier pages are left exactly as they were published.
Boulder, Larimer and Weld · September 2026
The northern Front Range: fewer sales, firmer prices, tighter supply
County-level statistics published by the Colorado Association of REALTORS. Every figure below is read off the published county report, and each report prints its own prior-September column, so nothing here is derived.
All three counties sold fewer single-family homes than a year ago, and the drops are steeper than Denver Metro’s: Larimer down 20.8 percent to 317 closings, Weld down 19.1 percent to 356, Boulder down 12.6 percent to 222. Prices did not follow them down. Boulder’s single-family median actually rose 3.6 percent to $829,000, while Larimer and Weld held within one percent of last September at $579,000 and $500,625.
The reason prices held is supply. Every northern county is tighter than Denver Metro’s 4.76 months: Boulder at 3.5 months, Larimer at 3.8, Weld at 3.7. Sellers are also holding the line on negotiation, with close-to-list ratios of 98.0, 98.6 and 98.8 percent. The attached segment is the softer side of each market, as it is in Denver: Weld’s attached inventory fell 34.1 percent year over year and its attached homes are now taking 91 days at the median.
September 2025September 2026
Source: Colorado Association of REALTORS county Local Market Update, September 2026, current as of October 5, 2026.
View the data
| County and property type | September 2025 | September 2026 |
|---|---|---|
| Boulder County, single family | 254 | 222 |
| Larimer County, single family | 400 | 317 |
| Weld County, single family | 440 | 356 |
| Boulder County, attached | 83 | 59 |
| Larimer County, attached | 100 | 85 |
| Weld County, attached | 47 | 44 |
September 2025September 2026
Source: Colorado Association of REALTORS county Local Market Update, September 2026, current as of October 5, 2026.
View the data
| County and property type | September 2025 | September 2026 |
|---|---|---|
| Boulder County, single family | 4.1 | 3.5 |
| Larimer County, single family | 3.9 | 3.8 |
| Weld County, single family | 3.6 | 3.7 |
| Boulder County, attached | 5.4 | 5.7 |
| Larimer County, attached | 4.5 | 4.4 |
| Weld County, attached | 6.2 | 4.8 |
September 2025September 2026
Source: Colorado Association of REALTORS county Local Market Update, September 2026, current as of October 5, 2026.
View the data
| County and property type | September 2025 | September 2026 |
|---|---|---|
| Boulder County, single family | $800,000 | $829,000 |
| Larimer County, single family | $585,000 | $579,000 |
| Weld County, single family | $502,258 | $500,625 |
| Boulder County, attached | $515,000 | $495,000 |
| Larimer County, attached | $446,000 | $398,000 |
| Weld County, attached | $363,000 | $356,250 |
A note on the source. Through September 2026 this page used PPAR and elevate MLS for Colorado Springs and the Colorado Association of REALTORS for the northern counties. From this issue forward the Association’s county reports are the single source for every county outside Denver Metro, so that month-to-month and county-to-county comparisons on this page are always like for like. Earlier pages are left exactly as they were published.
What this means for you
Heading into the fourth quarter
If you are buying
- You have 13,567 active listings and 4.76 months of supply to work with, and competition thins out through the holidays.
- Condos and townhomes are where the leverage is: 7.21 months of inventory and a median of $365,500.
- Ask about structure, not just price. Rate buydowns and seller-paid concessions are the live negotiation right now.
- Underwrite the attached segment with HOA dues and insurance included, not bolted on afterward.
If you are selling
- Homes are taking 32 days at the median, up from 21 in July. Price to today, not to July.
- The close-to-list ratio held at 98.45 percent, so a well-priced home still gets close to asking.
- Build buydowns and concessions into the pricing strategy up front. Snitker’s point is that those sellers find a ready audience.
- Above $1 million the picture is different again: new listings up +12.15% and a 21-day median.
Want to know what this means for your address?
Metro-wide numbers set the backdrop. What your home is worth, or what you can buy, comes down to your street, your price band and your timing. Grab a slot and we will walk through it.
Sources and method
Where these numbers come from
- Greater Denver Metro: DMAR Real Estate Market Trends Report, September 2026, published October 3, 2026. Statistics sourced from REcolorado. The July and August median-days-in-MLS points charted above are as published in the August 2026 report.
- Colorado Springs and El Paso County: Colorado Association of REALTORS Local Market Update for El Paso County, September 2026, current as of October 5, 2026. Earlier pages on this site sourced this county from PPAR and elevate MLS, which cover the wider Pikes Peak region, so those counts are not directly comparable to the county figures shown here.
- Boulder, Larimer and Weld counties: Colorado Association of REALTORS county Local Market Updates, September 2026, current as of October 5, 2026. These reports print the prior-September column alongside the current month, so no year-over-year figure on this page is derived.
Every figure on this page is read off the published source report and checked before it goes up. Where a region’s data is not out yet, or is still being verified, we say so and name the date rather than printing an estimate. We do not build back-series by working backwards from percentage changes. Months of inventory for the detached segment, the overall September median close price and the overall new-listings count were not published by DMAR this month, so they do not appear here.
Mike Rush and Bill Leeper · Your Colorado Home Group · Keller Williams Realty DTC · 719-440-8249
 Keller Williams Realty DTC